Insights on the Surplus & Off-Spec Chemical Market
Welcome to the SUR+ International knowledge hub, where we explore the forces shaping the global chemical industry and the growing role of surplus redistribution. From shifting tariff landscapes and plant closures to safe storage, sustainability, and supply chain resilience, our articles unpack the trends, risks, and opportunities that matter most to manufacturers, procurement leaders, and sustainability teams.
Whether you’re holding excess inventory you didn’t know was a recoverable asset, or sourcing reliable off-spec materials as a hedge against volatility, these articles offer practical perspective grounded in real market data. Dive in to discover how turning surplus chemicals into value can strengthen your bottom line, reduce your energy footprint, and build a more resilient operation.
By Shai Tsarfati, Co-Founder and CEO of Surplus International
The latest U.S. manufacturing data appears to tell two different stories about chemical inventory.
The Institute for Supply Management’s August 2026 survey reported that respondents in Chemical Products reduced inventories month on month. Chemical Products was also among the industries reporting customers’ inventories as too low. In the same industry summary, new orders and backlogs declined, although production and new export orders increased
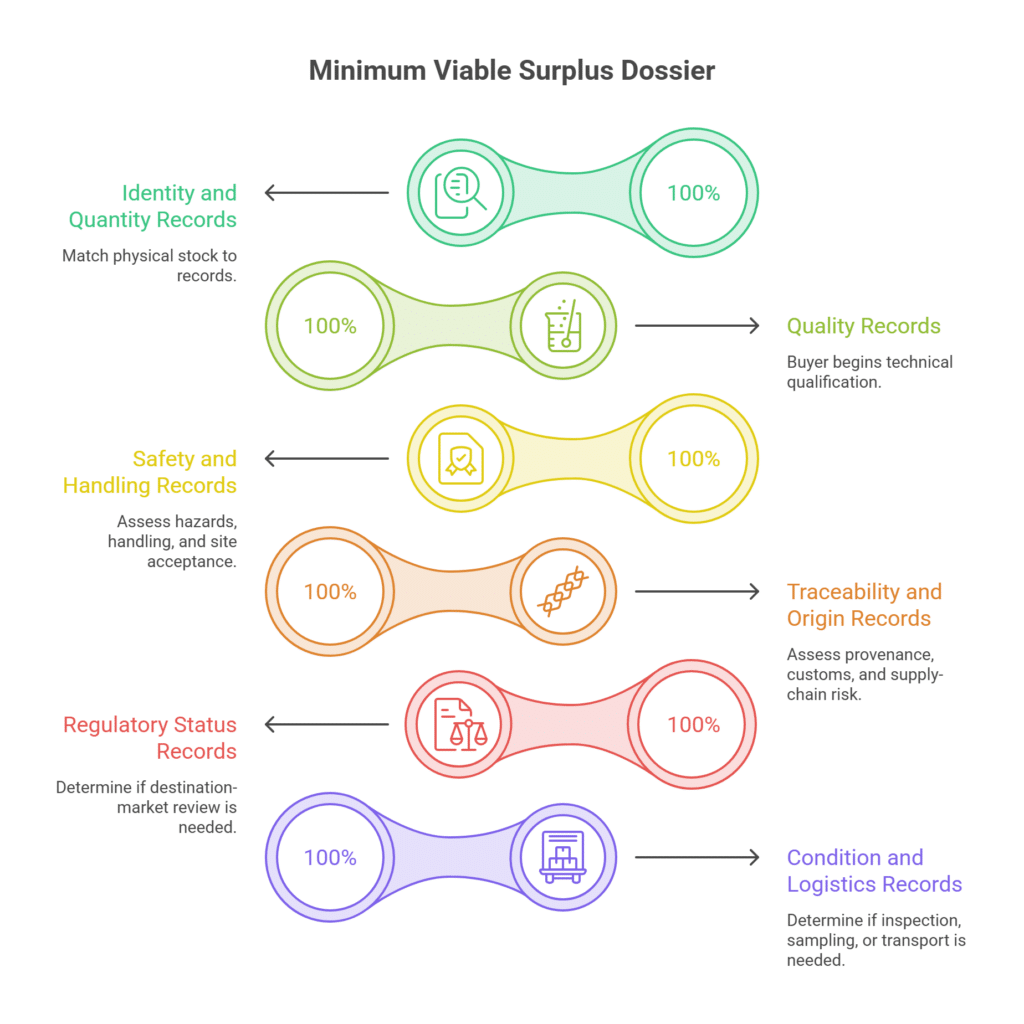
TL;DR: The EU’s Digital Product Passport infrastructure is now operational, although chemicals do not face a general mandatory 2029 deadline. The near-term issue for chemical companies is downstream data pull. As customers in regulated product sectors request more structured information, the secondary-market value of surplus stock will depend increasingly on preserved identity, quality, safety, traceability and regulatory records.
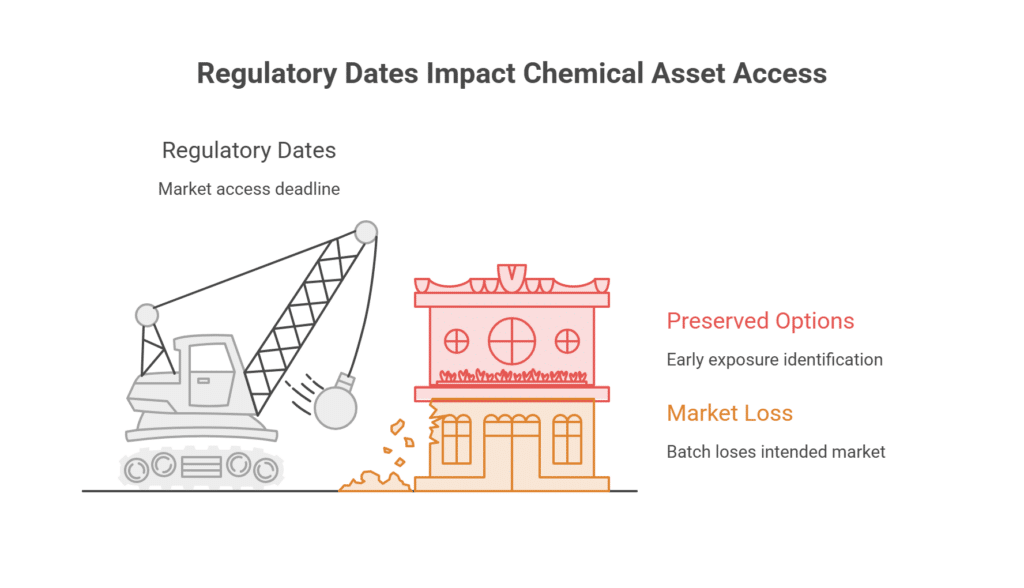
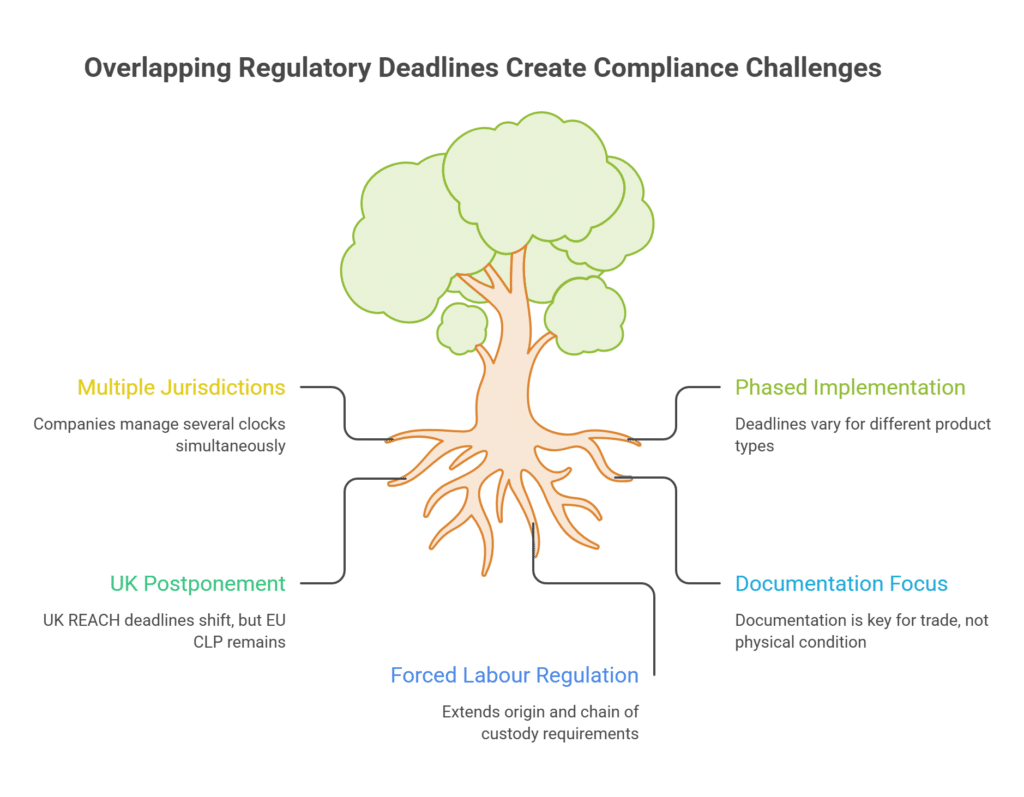
TL;DR: Chemical inventory has two clocks: physical stability and regulatory eligibility. Recent EU and UK cosmetics changes show that transition structures can differ sharply, while the EU’s revised REACH roadmap and the November 2026 CLP deadline keep the restriction and classification pipeline moving. Companies should add regulatory dates to slow-moving inventory reviews before a technically usable batch loses access to its intended market.
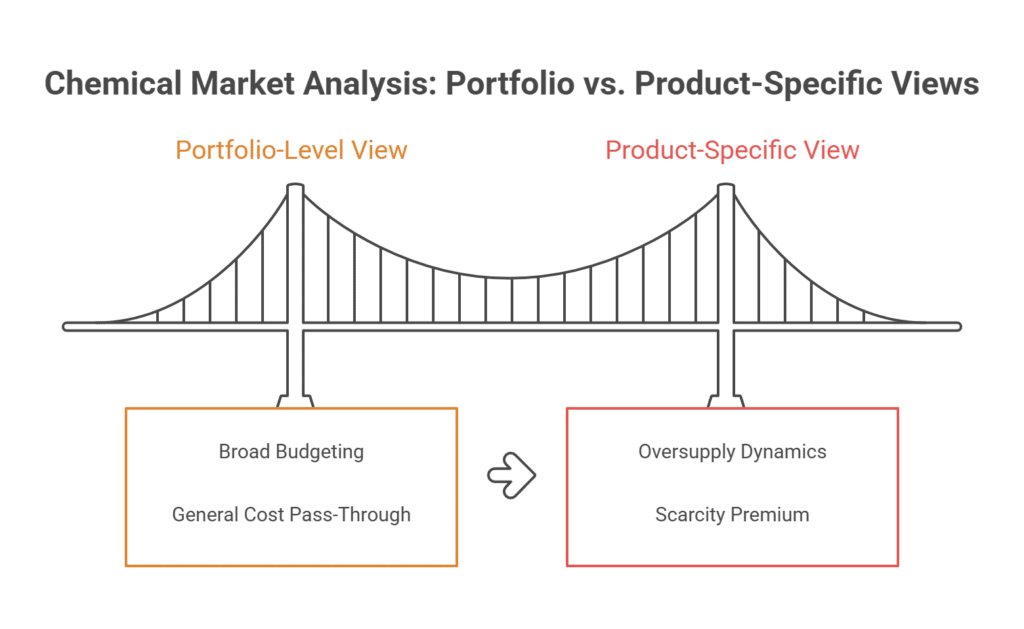
TL;DR: Preliminary May 2026 data showed a 791-million-pound monthly increase in US polyethylene inventory, while North American flexible slabstock polyol spot values had risen nearly 96% over ten weeks. These markets were responding to different production and supply constraints. Procurement teams should therefore manage exposure by molecule, grade, location and time window. Properly qualified secondary inventory can add flexibility, but it does not replace core contracts or technical and regulatory due diligence.
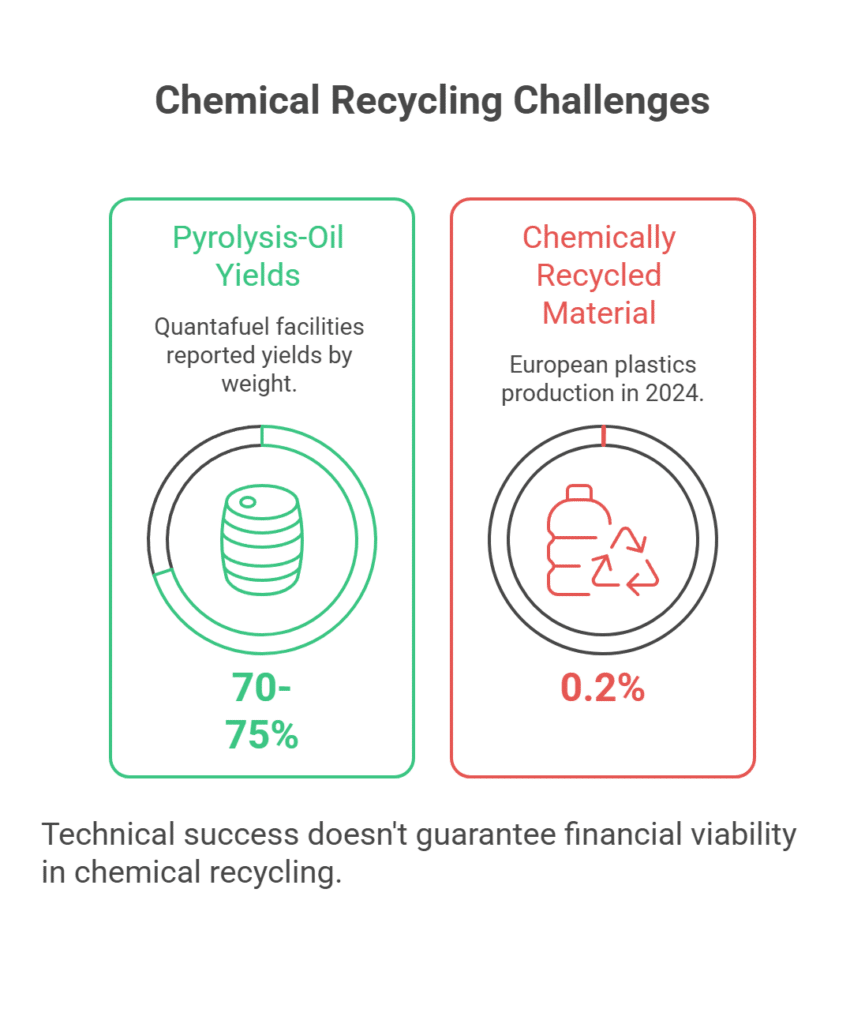
TL;DR: A series of 2026 closures and cancellations shows that plastics recycling can be technically feasible without being commercially secure. This is not an argument against recycling. It is an argument for a better sequence of decisions: for still-usable industrial inventory, assess direct reuse before spending more energy and capital on reprocessing. Genuine waste, contaminated material and unsuitable stock must continue through authorised recycling or disposal routes.
The circular economy depends on more than good chemistry. It also depends on collection, sorting, energy, infrastructure, offtake, policy and prices that allow the system to operate commercially.
This is the closing article in a four-part series. We began with the 1 November 2026 CLP transition and the idea that chemical inventory carries a regulatory expiry date alongside its physical one. We then argued that the next wave of surplus material will come from ownership change rather than plant closures. Most recently we looked at tariff volatility and why material already inside a destination border carries a certainty that an overseas quotation cannot.
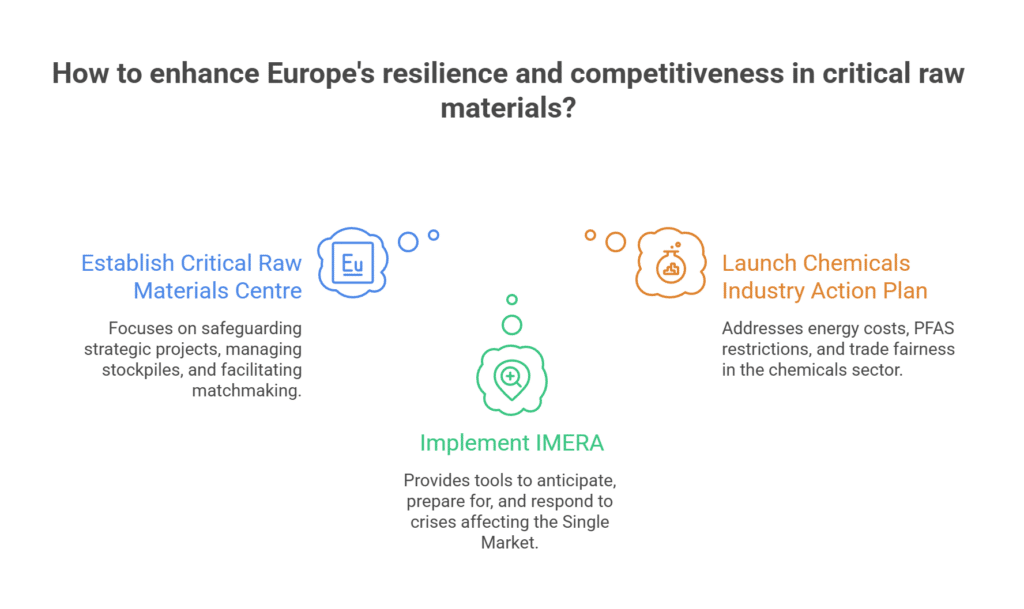
Each of those was a tactical observation. This one is different, because in June 2026 the European Commission did something that reframes the entire subject.
It built a public institution whose mandate is, in substance, a description of the secondary materials market.
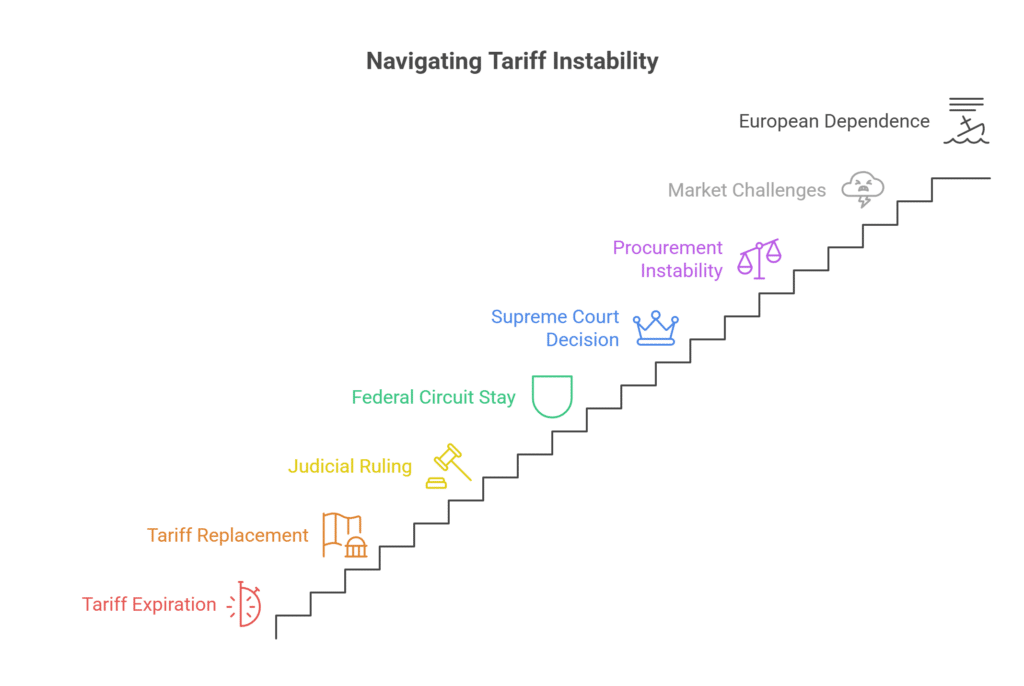
In our previous article we argued that the next wave of surplus material will come from ownership change rather than plant closures, and that the portfolio pruning following large divestitures and mergers will release inventory quietly over the coming two years. That was a question of supply. This article is about the other side of the same transaction: what has happened to the arithmetic of buying, and why the location of material has become a financial variable rather than a logistical one.
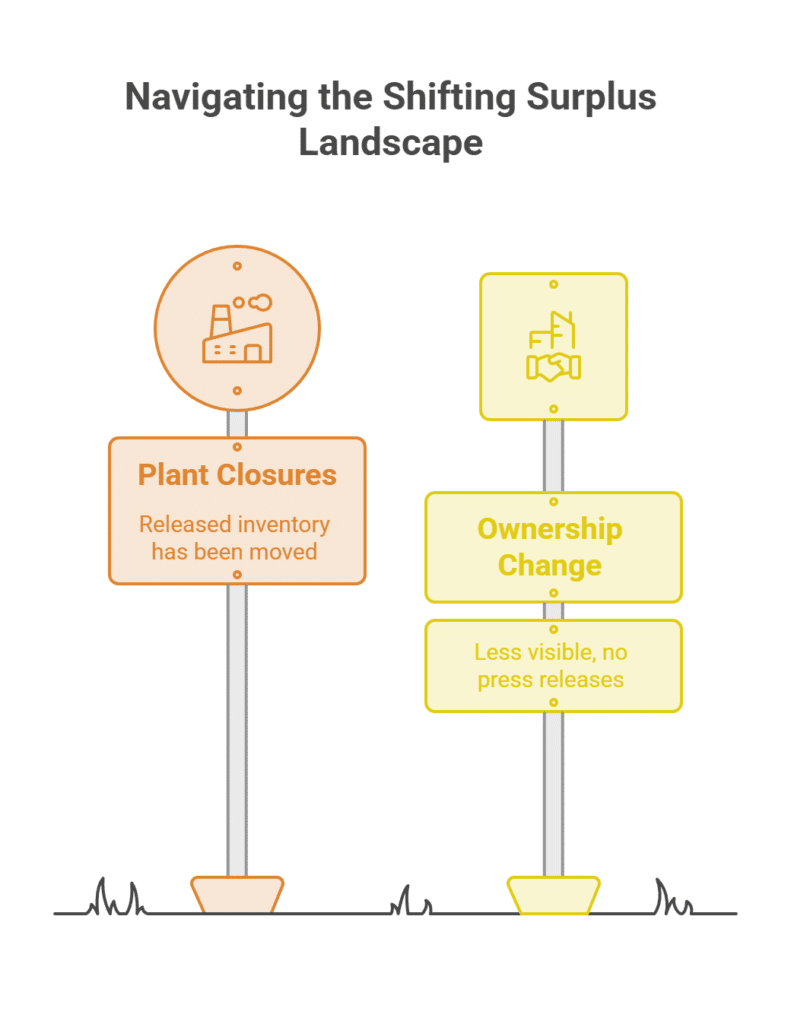
In our previous article we looked at the 1 November 2026 CLP transition and why dormant European inventory has a regulatory expiry date as well as a physical one. That piece was about material already sitting in warehouses. This one is about where the next tranche of that material will come from, and the answer has changed.
In our previous analysis of the great chemical restructuring, we looked at how plant closures and portfolio exits are releasing unprecedented volumes of high quality material into the surplus market. That discussion assumed something worth examining more closely: that a drum of on-spec material holds its value until someone buys it or its shelf life expires. For a significant share of European inventory, that assumption stops being true on 1 November 2026.